

The State of Crypto Liquidity: A Tale of Two Markets One Year Post-Crash
Twelve months have passed since the catastrophic “10/10” flash crash, a watershed moment that triggered the most significant liquidation event in the history of digital assets. As the market reflects on this anniversary, the underlying infrastructure of the crypto ecosystem reveals a stark bifurcation: while the industry’s heavyweights have successfully fortified their positions, the broader altcoin market remains trapped in a fragile state of decay.
Market Depth: The Resilience of BTC and ETH
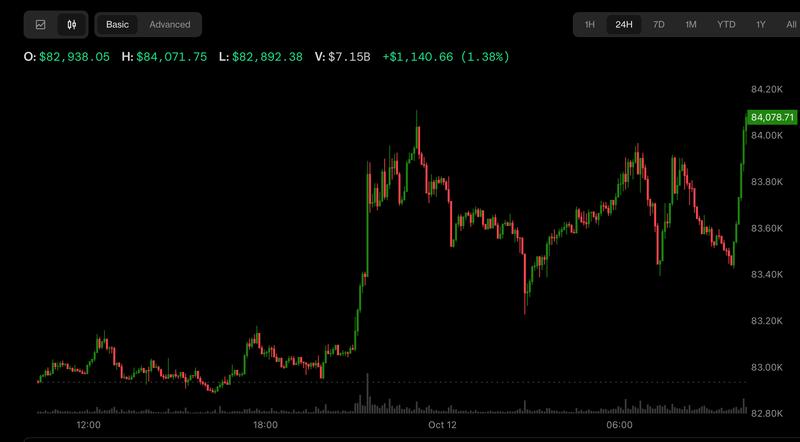
Data from the past year indicates that Bitcoin (BTC) and Ether (ETH) have undergone a robust recovery in terms of market depth. Unlike the immediate aftermath of the October 2025 volatility, current order books for these two assets are significantly more substantial than they were at the start of 2025 or 2026.
Crucially, this isn’t merely a byproduct of fluctuating asset prices. When measured in dollar terms, the depth has expanded, signaling that institutional market makers have returned with increased capital commitments. This influx of liquidity acts as a shock absorber, theoretically insulating the two largest assets from the kind of extreme, rapid price swings that characterized the 2025 crash.
The Altcoin Liquidity Gap
Conversely, the narrative for smaller-cap tokens is far more concerning. While Bitcoin and Ether have seen their order books thicken, altcoin liquidity has been on a persistent downward trajectory since the beginning of 2025.
This decline is often obscured by the volatility of token prices; however, when stripping away the noise of market valuation, the actual dollar-denominated depth has eroded steadily. This creates a “hollow” market environment where even moderate sell orders can trigger outsized price slippage, leaving investors in smaller projects exposed to heightened volatility risks.
Trading Volume Trends
The broader health of the spot market remains a mixed bag. Current weekly spot trading volumes are still hovering at roughly one-third of the levels seen during the chaotic week of the 10/10 crash.
Despite this significant contraction, there is a glimmer of optimism. Trading activity has seen a modest resurgence, effectively doubling from the cyclical lows observed in August 2026. While this suggests a slow return of retail and institutional interest, the market has yet to reclaim the peak momentum seen in October 2025.
Key Takeaways:
* Capital Influx: BTC and ETH order books are deeper than pre-crash levels, reflecting renewed confidence from liquidity providers.
* Altcoin Vulnerability: Dollar-based liquidity for altcoins continues to shrink, increasing the risk of flash-crash scenarios for smaller assets.
* Volume Recovery: While spot trading volume is significantly lower than the 2025 peak, the recent doubling from August lows indicates a gradual, albeit cautious, market stabilization.
As the industry moves forward, the divergence between the “blue-chip” assets and the long tail of altcoins will likely remain a defining feature of the market’s plumbing. Investors should remain cognizant that while the foundation for Bitcoin and Ether has been reinforced, the altcoin sector continues to operate on thinner ice.